Understanding the 2026 Capital Gains Tax Landscape: Strategies for Smart Investment Dispositions
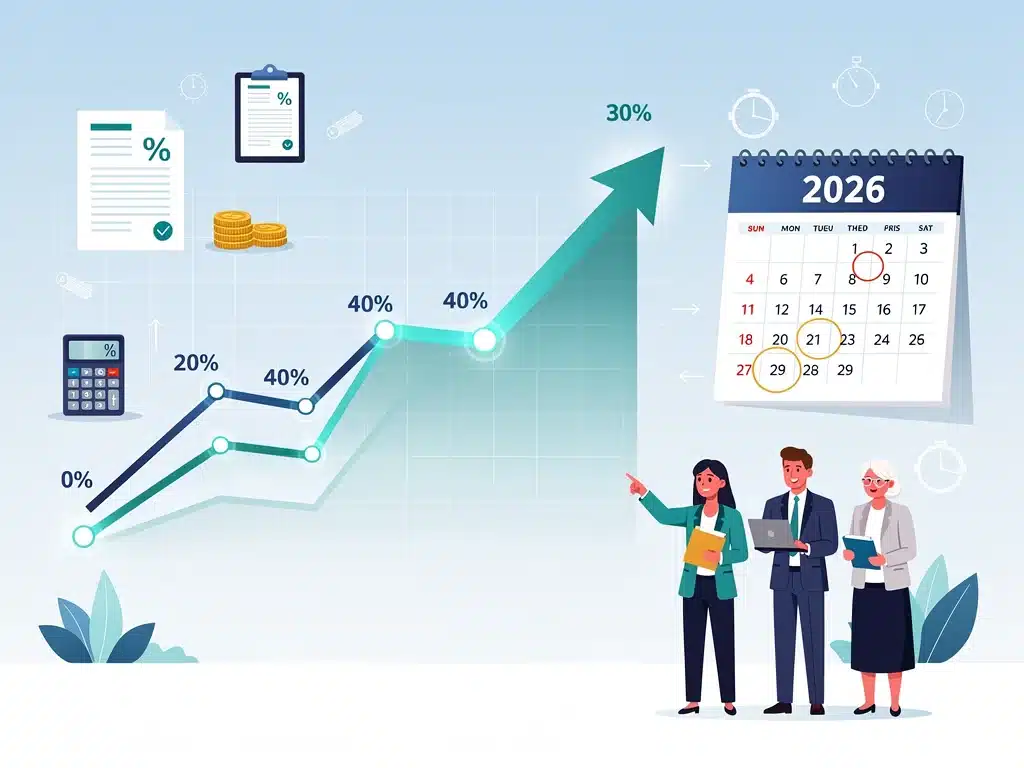
Are you preparing to liquidate appreciated investments or rebalance your portfolio this year? Navigating the 2026 Capital Gains Tax landscape is crucial for timing your asset sales to minimize liabilities and preserve portfolio value.
Updated federal inflation adjustments to income thresholds mean strategic planning can significantly lower your tax burden on realized gains.
Understanding the spread between short-term rate limits and preferential long-term brackets allows you to structure exit timing advantageously.
By coordinating asset holding periods and aligning dispositions with bracket boundaries, investors can avoid unnecessary bracket creep and protect net investment income.
Tactical moves like tax-loss harvesting and utilizing lower marginal tiers safeguard your long-term wealth. Executing well-timed investment liquidations under current statutory rules ensures you keep more of your investment returns.
The Evolving Tax Environment for Capital Gains
The discussion around the 2026 Capital Gains Tax reflects broader governmental efforts to potentially adjust revenue streams and address economic priorities. These conversations often involve intricate legislative proposals that could reshape investment profitability.
Investors are closely watching for definitive announcements, as even minor adjustments to tax rates or rules can have substantial long-term implications. Understanding the proposed mechanisms and their potential reach is crucial for informed decision-making.
The current landscape suggests a period of anticipation and strategic re-evaluation for many, as they weigh the potential impacts on their existing and future investment dispositions. This proactive stance is vital for maintaining financial health.
Key Legislative Proposals and Potential Changes
Several legislative proposals are currently under consideration that could influence the 2026 Capital Gains Tax. These proposals often include adjustments to the tax rates themselves, changes to holding periods for long-term capital gains, or modifications to exemptions and deductions.
For instance, some discussions revolve around increasing the top marginal capital gains tax rate for high-income earners, potentially aligning it more closely with ordinary income tax rates. This would represent a significant shift from the historical differentiation between the two types of income.
Another area of focus involves potential changes to the step-up in basis at death, which currently allows heirs to inherit assets at their fair market value, thereby avoiding capital gains tax on accumulated appreciation. Any alteration to this rule could have profound intergenerational wealth transfer implications.
- Proposals may include higher tax rates for specific income brackets.
- Changes to long-term capital gains holding periods are being discussed.
- Modifications to the step-up in basis rule at death could be significant.
The precise details of these proposals are still subject to negotiation and amendment, making it imperative for investors to remain agile in their planning. Monitoring official legislative channels and expert analysis is critical during this fluid period.
Understanding the Impact on Investment Dispositions
The potential changes to the 2026 Capital Gains Tax directly influence how investors strategize their asset sales and transfers. Dispositions that might have been tax-efficient under current rules could become less so, necessitating a fresh approach.
This includes re-evaluating the timing of sales, especially for highly appreciated assets, and considering alternative strategies like gifting or charitable contributions. The goal is to minimize tax liabilities while maximizing investment returns.
Investors must move beyond traditional disposition methods and explore more sophisticated techniques that align with the anticipated tax landscape. Proactive engagement with financial advisors becomes paramount in this scenario.
Analyzing Short-Term vs. Long-Term Capital Gains
The distinction between short-term and long-term capital gains is fundamental to the current tax system, and it is an area that could see significant adjustments under the 2026 Capital Gains Tax framework. Currently, assets held for less than one year are subject to ordinary income tax rates, while those held longer benefit from lower rates.
Should the holding period for long-term capital gains be extended, or if the preferential rates for long-term gains are reduced, investors would need to adjust their investment horizons. This could deter short-term trading in favour of longer-term strategies to achieve more favourable tax treatment.
The economic implications of such changes are broad, potentially influencing market liquidity and investor behaviour. Understanding these nuances is crucial for crafting effective disposition strategies ahead of 2026.
- Short-term gains are taxed at ordinary income rates.
- Long-term gains currently enjoy preferential tax rates.
- Potential changes could extend holding periods or reduce preferential rates.
These distinctions will remain a cornerstone of capital gains taxation, but their specific parameters could shift, demanding careful attention from all investors. Adapting to these potential changes proactively is a smart move.
Strategies for Smart Investment Dispositions
Navigating the anticipated 2026 Capital Gains Tax landscape requires a strategic approach to investment dispositions. This involves more than just selling assets; it encompasses a holistic view of your portfolio and financial goals.
Implementing strategies such as tax-loss harvesting, utilizing tax-advantaged accounts, and carefully timing sales can significantly mitigate potential tax burdens. These tactics are designed to optimize your net returns.
The key is to develop a comprehensive plan that considers individual circumstances, risk tolerance, and long-term financial objectives. A tailored strategy will be far more effective than a one-size-fits-all approach.
Tax-Loss Harvesting and Portfolio Rebalancing
Tax-loss harvesting is a time-tested strategy that involves selling investments at a loss to offset capital gains and, potentially, a limited amount of ordinary income. In anticipation of the 2026 Capital Gains Tax, this strategy could become even more valuable.
By strategically realizing losses, investors can reduce their taxable income, thereby lowering their overall tax liability. This approach is particularly effective when used in conjunction with portfolio rebalancing, allowing investors to maintain their desired asset allocation while optimizing tax outcomes.
Rebalancing involves adjusting your portfolio back to its original target asset allocation, often by selling assets that have performed well and buying those that have underperformed. Combining this with tax-loss harvesting can create a powerful synergy for tax efficiency.
- Sell losing investments to offset capital gains.
- Offset up to $3,000 of ordinary income annually with net losses.
- Rebalance portfolio to maintain desired asset allocation.
The strategic timing of these actions, especially towards the end of the tax year or in anticipation of new tax rules, is critical. Consulting with a financial advisor can help maximize the benefits of these strategies.
Utilizing Tax-Advantaged Accounts and Vehicles
For many investors, leveraging tax-advantaged accounts will be a cornerstone of their strategy for the 2026 Capital Gains Tax. These accounts offer various benefits, including tax-deferred growth or tax-free withdrawals, which can significantly reduce capital gains exposure.
Retirement accounts such as 401(k)s and IRAs, as well as health savings accounts (HSAs), provide powerful mechanisms to grow investments without immediate tax implications. Understanding the nuances of each account type is essential.
Beyond traditional retirement vehicles, exploring other tax-efficient investment structures can further enhance your financial planning. These options provide additional layers of protection against rising tax rates.
Exploring Roth Conversions and HSAs
Roth conversions, where funds are moved from a traditional IRA to a Roth IRA, could be a compelling strategy in the lead-up to the 2026 Capital Gains Tax. While the conversion itself triggers ordinary income tax, future qualified withdrawals from the Roth IRA are tax-free, including any capital gains.
If investors anticipate higher tax rates in the future, paying taxes now at potentially lower rates through a Roth conversion could be advantageous. This strategy requires careful consideration of one’s current and projected income levels.
Health Savings Accounts (HSAs) also offer a triple tax advantage: tax-deductible contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses. For those eligible, HSAs can serve as an excellent long-term investment vehicle, shielding capital gains from taxation.
- Roth conversions can lock in current tax rates for future tax-free growth.
- HSAs offer tax-deductible contributions, tax-free growth, and tax-free withdrawals.
- Consider current and future income levels for Roth conversion decisions.
These tax-advantaged vehicles provide powerful tools for managing capital gains exposure and should be thoroughly integrated into any comprehensive financial plan. Their benefits extend far beyond just tax season.
Real Estate and Business Asset Considerations
The 2026 Capital Gains Tax landscape will also have significant implications for real estate investors and business owners. The disposition of properties and business assets often involves substantial capital gains, making careful planning paramount.
Strategies like 1031 exchanges for real estate, which allow for deferral of capital gains tax when reinvesting in similar properties, may become even more critical. Understanding the rules and potential changes to these provisions is vital.
For business owners, the sale of a company or its assets requires meticulous tax planning to minimize the capital gains hit. This often involves working with tax professionals well in advance of any transaction.
1031 Exchanges and Qualified Opportunity Zones
A 1031 exchange, also known as a like-kind exchange, allows real estate investors to defer capital gains taxes when selling an investment property and reinvesting the proceeds into another similar property.
As the 2026 Capital Gains Tax approaches, the utility of 1031 exchanges could be amplified for those looking to maintain their real estate portfolios without incurring immediate tax liabilities.
However, it is crucial to stay informed about any potential legislative changes that could modify or restrict the use of 1031 exchanges. These provisions have been subject to scrutiny in past tax reform discussions, and their future remains a point of interest.
Qualified Opportunity Zones (QOZs) offer another powerful tool for deferring and potentially reducing capital gains taxes.
By investing capital gains into businesses or property located in designated QOZs, investors can defer taxes on the original gain and potentially eliminate taxes on new gains from the QOZ investment if held for a sufficient period.
- 1031 exchanges defer capital gains tax on like-kind real estate reinvestments.
- QOZs offer deferral and potential elimination of capital gains tax.
- Monitor legislative changes for both 1031 exchanges and QOZs.
These specialized strategies provide significant opportunities for tax efficiency but require careful adherence to complex rules and regulations. Expert guidance is highly recommended when considering these options.
The Role of Professional Financial Advice
Given the complexities and potential shifts in the 2026 Capital Gains Tax, engaging with professional financial advisors and tax experts is more important than ever. Their expertise can provide invaluable guidance tailored to individual circumstances.
A knowledgeable advisor can help interpret legislative changes, forecast their impact, and develop bespoke strategies for smart investment dispositions. This personalized approach ensures that all aspects of your financial situation are considered.
Attempting to navigate these intricate tax waters alone can lead to missed opportunities or costly mistakes. Professional guidance offers peace of mind and optimized outcomes.
Choosing the Right Advisor for Tax Planning
Selecting a financial advisor who specializes in tax planning and investment dispositions is paramount when preparing for the 2026 Capital Gains Tax. Look for professionals with a strong track record and up-to-date knowledge of current and proposed tax laws.
Ensure the advisor understands your specific financial goals, risk tolerance, and investment portfolio. A good advisor will work collaboratively, providing clear explanations and transparent advice, rather than simply dictating strategies.
Consider advisors who are fiduciaries, meaning they are legally obligated to act in your best interest. This ensures that their recommendations are aligned with your financial well-being, rather than their own commissions or incentives.
- Seek advisors specializing in tax planning and investment dispositions.
- Ensure they understand your financial goals and risk tolerance.
- Prioritize fiduciaries who are legally obligated to act in your best interest.
The right advisor can be an indispensable partner in navigating the complexities of the 2026 Capital Gains Tax and optimizing your financial future. Their insights can make a significant difference.
Anticipating Future Tax Law Developments
The landscape surrounding the 2026 Capital Gains Tax is dynamic, with ongoing discussions and potential legislative changes. Staying informed about these developments is crucial for effective long-term financial planning.
Tax laws are rarely static, and what is proposed today may evolve significantly before becoming law. Continuous monitoring of legislative bodies and official announcements is essential for investors.
Adopting a flexible and adaptive approach to financial strategy allows investors to pivot quickly in response to new information. This proactive stance is the best defense against unexpected tax burdens.
Monitoring Legislative Progress and Official Announcements
As the 2026 Capital Gains Tax draws closer, closely monitoring legislative progress in Congress and official announcements from the Treasury Department and IRS will be vital. These sources provide the most accurate and timely information regarding potential tax law changes.
Subscribing to reputable financial news outlets and tax policy newsletters can also help investors stay abreast of developments. Expert analysis often provides valuable context and interpretation of complex legislative language.
Participating in webinars or seminars hosted by financial planning firms can offer direct insights from professionals who are actively tracking these changes. These resources can help clarify ambiguities and provide practical advice.
- Follow legislative progress in Congress closely.
- Subscribe to official announcements from the Treasury and IRS.
- Engage with reputable financial news and expert analysis.
A proactive and informed approach to tracking these developments will empower investors to make timely and strategic adjustments to their investment dispositions. The goal is always to be ahead of the curve.
| Key Point | Brief Description |
|---|---|
| Tax Landscape Evolution | Potential legislative changes to capital gains rates and rules are under discussion for 2026. |
| Strategic Dispositions | Investors need to re-evaluate timing of sales and explore tax-efficient strategies proactively. |
| Tax-Advantaged Accounts | Utilizing 401(k)s, IRAs, Roth conversions, and HSAs can mitigate tax impact. |
| Professional Guidance | Engaging financial and tax experts is crucial for personalized planning and optimized outcomes. |
Frequently Asked Questions About the 2026 Capital Gains Tax
The primary concern revolves around potential legislative changes that could increase capital gains tax rates or alter existing rules, such as holding periods or the step-up in basis. These shifts could significantly impact investment profitability and necessitate new disposition strategies for investors.
Investors can prepare by reviewing their portfolios, considering strategies like tax-loss harvesting, and utilizing tax-advantaged accounts. Consulting with a financial advisor specializing in tax planning is also highly recommended to develop a personalized and proactive strategy.
No, the impact will likely vary based on income levels, asset types, and investment timelines. Proposed changes often target specific income brackets or asset classes. High-net-worth individuals and those with significant appreciated assets may experience a more pronounced effect.
Real estate investors can explore strategies such as 1031 exchanges to defer capital gains tax when reinvesting in similar properties. Additionally, investing in Qualified Opportunity Zones offers potential deferral and reduction of capital gains, but careful adherence to rules is essential.
Reliable information can be found through official government sources like the Treasury Department and IRS, reputable financial news outlets, and expert analyses from certified financial planners and tax attorneys. Staying updated through these channels is crucial for informed decision-making.
Looking Ahead
The ongoing discussions surrounding the 2026 Capital Gains Tax underscore the importance of vigilant financial planning. While the final legislative landscape is still taking shape, a proactive and informed approach remains the most effective strategy for investors.
Monitoring official announcements and engaging with financial professionals will be key to adapting to any changes and ensuring smart investment dispositions. This continuous engagement helps mitigate risks and capitalize on opportunities within the evolving tax environment.