Optimizing Your 2026 HSA: Maximize Tax Benefits & Growth
Latest developments on Optimizing Your 2026 Health Savings Account (HSA) for Maximum Tax Benefits and Future Growth, with key facts, verified sources and what readers need to monitor next in Estados Unidos, presented clearly in Inglês (Canadá) (en-CA).
Optimizing Your 2026 Health Savings Account (HSA) for Maximum Tax Benefits and Future Growth is shaping today’s agenda with new details released by officials and industry sources. This update prioritizes what changed, why it matters and what to watch next, in a straightforward news format.
Understanding the 2026 HSA Landscape
The Health Savings Account (HSA) continues to be a powerful financial tool, particularly for those enrolled in high-deductible health plans (HDHPs). For 2026, understanding the updated contribution limits, eligibility criteria, and regulatory changes is paramount for effective planning.
These accounts offer a unique triple-tax advantage: tax-deductible contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses. This makes them an invaluable asset for both immediate healthcare costs and long-term retirement savings.
Staying informed about the specific parameters for 2026 will allow individuals and families to strategically maximize their contributions and leverage the full scope of benefits available, aligning with broader financial goals.
Key Changes and Contribution Limits for 2026
As we approach 2026, it is crucial to recognize any potential adjustments to HSA contribution limits and eligibility requirements. These annual updates by the IRS directly impact how much individuals can save and invest tax-free.
While specific 2026 figures are yet to be finalized by the IRS, historical trends suggest an upward adjustment. Planning based on projected increases allows for proactive financial structuring, ensuring you can contribute the maximum allowable amount.
Monitoring official IRS announcements for the 2026 limits is essential. These figures will dictate the ceiling for tax-advantaged savings, directly influencing strategies for Optimizing Your 2026 Health Savings Account (HSA) for Maximum Tax Benefits and Future Growth.
Projected Contribution Increases
Based on inflation and historical adjustments, experts anticipate an increase in both individual and family contribution limits for 2026. These projections are critical for those planning their annual savings.
Catch-up contributions for those aged 55 and older are also expected to remain a vital component, offering an additional opportunity to bolster savings. This provision is especially beneficial for individuals nearing retirement who may have higher medical expenses.
- Individual Contribution Limit: Expect an increase from current levels.
- Family Contribution Limit: Anticipate a proportionate rise for family plans.
- Catch-Up Contributions (Age 55+): Likely to remain stable at an additional amount per year.
Leveraging the Triple-Tax Advantage
The core appeal of an HSA lies in its unparalleled triple-tax advantage, a feature central to Optimizing Your 2026 Health Savings Account (HSA) for Maximum Tax Benefits and Future Growth. Understanding how each component works is key to maximizing its value.
Contributions made to an HSA are tax-deductible, reducing your taxable income in the year they are made. This immediate tax break provides an incentive for consistent savings and investment.
Moreover, the funds within an HSA grow tax-free, meaning any investment gains, dividends, or interest are not subject to annual taxation. This allows for significant compounding over time, enhancing long-term wealth accumulation.
Tax-Free Withdrawals for Qualified Expenses
Perhaps the most significant benefit is the ability to withdraw funds tax-free for qualified medical expenses at any time. This includes deductibles, co-payments, prescriptions, and a wide range of other healthcare costs.
Maintaining meticulous records of medical expenses is crucial, especially if you plan to let your HSA grow and reimburse yourself later. This strategy allows your investments to compound for a longer period.
- Deductible Contributions: Reduce current year’s taxable income.
- Tax-Free Growth: Investments grow without annual tax implications.
- Tax-Free Withdrawals: For qualified medical expenses, both now and in retirement.
Strategic Investment within Your HSA
Many individuals use their HSA solely for immediate medical expenses, missing out on its powerful investment potential. For Optimizing Your 2026 Health Savings Account (HSA) for Maximum Tax Benefits and Future Growth, treating it as an investment vehicle is paramount.
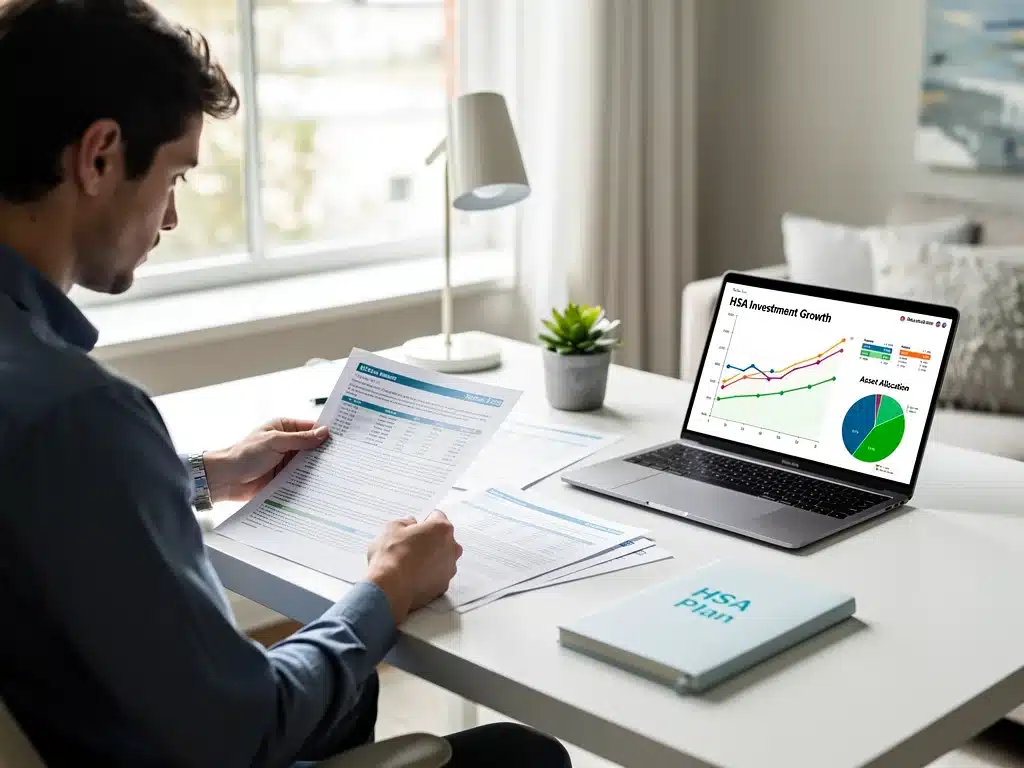
Once your HSA balance reaches a certain threshold, often around $1,000, most providers allow you to invest a portion of the funds in various options like mutual funds, ETFs, or stocks. This enables your money to grow significantly over decades.
Choosing the right investment strategy within your HSA should align with your risk tolerance and financial goals, considering that these funds are ultimately intended for future healthcare costs, which can be substantial in retirement.
Selecting Investment Options
HSA providers offer a range of investment choices, from conservative options like money market funds to more aggressive equity funds. Diversification is key, even within an HSA.
Consider your time horizon; if retirement is decades away, a more growth-oriented portfolio might be suitable. As you approach retirement, you might shift towards more conservative investments to preserve capital.
Researching the fees associated with different investment options is also critical, as high fees can erode returns over time. Opt for low-cost index funds or ETFs where available.
HSAs as a Retirement Planning Tool
Beyond immediate healthcare needs, HSAs serve as an exceptional retirement planning vehicle, often dubbed the “stealth IRA.” After age 65, withdrawals for non-medical expenses are taxed as ordinary income, similar to a traditional IRA.
However, withdrawals for qualified medical expenses remain tax-free at any age, even in retirement. This flexibility makes Optimizing Your 2026 Health Savings Account (HSA) for Maximum Tax Benefits and Future Growth a cornerstone of comprehensive financial planning.
The ability to pay for current medical expenses out-of-pocket while allowing your HSA investments to grow untouched offers a unique advantage. This strategy maximizes the compounding effect, resulting in a larger, tax-free pool of funds for future healthcare needs.
Integrating HSA with Other Retirement Accounts
For a holistic retirement strategy, integrate your HSA planning with your 401(k) and IRA contributions. Prioritizing HSA contributions, especially if you can afford to pay current medical expenses from other funds, can be highly advantageous.
Consider using your HSA to cover healthcare costs in retirement, freeing up funds from your 401(k) or IRA for other expenses. This creates a diversified approach to funding your post-employment years.
The flexibility of HSA funds means they can act as a safety net for unexpected medical costs, reducing the need to dip into other retirement savings that may be earmarked for living expenses.
Maximizing Your HSA for Future Growth
To truly maximize the future growth of your HSA, consistent contributions and a long-term investment mindset are essential. Avoid the temptation to deplete the account for minor, immediate medical costs if you have other means to cover them.
Focus on contributing the maximum allowable amount each year, especially taking advantage of catch-up contributions if eligible. This disciplined approach builds a substantial fund over time.
Regularly review your investment allocations within the HSA to ensure they align with your financial objectives and risk tolerance. Rebalancing periodically can help maintain your desired asset mix and contribute to Optimizing Your 2026 Health Savings Account (HSA) for Maximum Tax Benefits and Future Growth.
Understanding Qualified Medical Expenses
A thorough understanding of what constitutes a qualified medical expense is vital for tax-free withdrawals. The IRS provides extensive guidance on this, which includes a wide array of services, equipment, and treatments.
Keeping detailed records of all medical expenses, even those paid out-of-pocket, allows for future tax-free reimbursement from your HSA. This is a powerful strategy for letting your HSA grow for decades.
Periodically review IRS Publication 502, “Medical and Dental Expenses,” for the most up-to-date information on eligible expenses. This ensures all withdrawals are compliant and tax-free.
Navigating Eligibility and Enrollment for 2026
Eligibility for an HSA is tied directly to enrollment in a high-deductible health plan (HDHP). For 2026, understanding the specific criteria for what constitutes an HDHP is crucial for both initial enrollment and continued contributions.
HDHP definitions typically involve minimum deductible amounts and maximum out-of-pocket limits, which are adjusted annually by the IRS. Ensuring your health plan meets these thresholds is the first step in Optimizing Your 2026 Health Savings Account (HSA) for Maximum Tax Benefits and Future Growth.
Additionally, you generally cannot be covered by any other non-HDHP health insurance, including Medicare, or be claimed as a dependent on someone else’s tax return. These rules are strict and must be adhered to for continued eligibility.
Employer-Sponsored vs. Individual HSAs
Many employers offer HDHPs with an accompanying HSA, often contributing to the account. Employer contributions are also tax-free to the employee, further enhancing the benefit.
If your employer does not offer an HSA-eligible plan, or if you are self-employed, you can open an individual HSA. The tax benefits remain the same, though you are responsible for all contributions.
When choosing between employer-sponsored and individual plans, consider factors like administrative fees, investment options, and any employer contributions, as these can significantly impact your overall HSA value.
Common Pitfalls to Avoid in 2026
While HSAs offer substantial benefits, certain pitfalls can diminish their effectiveness. Avoiding these common mistakes is essential for Optimizing Your 2026 Health Savings Account (HSA) for Maximum Tax Benefits and Future Growth.
One common error is failing to invest HSA funds, leaving them in a low-interest cash account. This negates the significant tax-free growth potential, especially over long periods.
Another pitfall is making non-qualified withdrawals before age 65, which incur both income tax and a 20% penalty. Understanding qualified expenses and maintaining proper documentation is critical to avoid these penalties.
Documentation and Record-Keeping
Meticulous record-keeping is paramount for HSAs. Save all receipts for qualified medical expenses, even if you pay for them out-of-pocket and plan to reimburse yourself years later.
These records serve as proof that your withdrawals were for qualified expenses, protecting you in case of an IRS audit. Digital records are often easiest to maintain and access.
Failing to maintain adequate documentation can lead to tax complications and potential penalties if you cannot substantiate that withdrawals were for eligible medical costs.
| Key Point | Brief Description |
|---|---|
| Triple-Tax Advantage | Contributions are tax-deductible, growth is tax-free, and qualified withdrawals are tax-free. |
| Investment Potential | Invest HSA funds for long-term growth, treating it as a retirement asset. |
| Retirement Savings | After age 65, funds can be used for non-medical expenses with income tax, or tax-free for medical. |
| Eligibility & Limits | Must be enrolled in an HDHP; monitor IRS for 2026 contribution limits. |
Frequently Asked Questions About 2026 HSAs
The primary benefits for Optimizing Your 2026 Health Savings Account (HSA) include its triple-tax advantage: tax-deductible contributions, tax-free growth on investments, and tax-free withdrawals for qualified medical expenses. It also serves as a powerful tool for long-term retirement planning, offering significant financial flexibility.
To maximize contributions, stay updated on the official IRS limits for 2026 and aim to contribute the maximum allowable amount. If you are 55 or older, take advantage of the catch-up contribution provision. Consistent, full contributions are key to long-term growth.
Yes, once your HSA balance reaches a certain threshold, most providers allow you to invest funds in various options like mutual funds or ETFs. Investing your HSA funds is crucial for Optimizing Your 2026 Health Savings Account (HSA) for Maximum Tax Benefits and Future Growth, leveraging tax-free growth.
Unused HSA funds roll over year after year and continue to grow tax-free. After age 65, you can withdraw funds for any purpose without penalty, though non-medical withdrawals will be subject to ordinary income tax, similar to a traditional IRA.
To be eligible for an HSA in 2026, you must be enrolled in a high-deductible health plan (HDHP) and not have other non-HDHP health coverage. You also cannot be claimed as a dependent on someone else’s tax return or be enrolled in Medicare.
Perspectives for 2026 and Beyond
The landscape for Optimizing Your 2026 Health Savings Account (HSA) for Maximum Tax Benefits and Future Growth continues to evolve, making proactive engagement vital. Financial experts and policy analysts emphasize that HSAs are not merely spending accounts but powerful investment vehicles that demand strategic attention.
Monitoring legislative developments and IRS guidance will be crucial for adapting strategies and ensuring compliance. The long-term trajectory of healthcare costs reinforces the need for robust savings mechanisms, positioning HSAs as indispensable tools for financial resilience.
Individuals should view their HSA as a dynamic asset, requiring regular review of investment performance and contribution strategies to truly harness its full potential for both immediate and future healthcare needs, integrating it seamlessly into broader wealth management plans.